

It often starts the same way: a renewal notice arrives. The premium has increased slightly, the debit order looks fine, and life moves on. Months later, a storm, fire, or theft claim reveals an uncomfortable truth. The cover no longer reflects what it would actually cost to rebuild, replace, or fully recover.
Insurance renewal is widely misunderstood as confirmation that cover remains adequate, regardless of changes. In reality, renewal is one of the most important personal risk management moments of the year. Homes change, lifestyles evolve, asset values increase, and risk environments shift. Without review, policies can quietly fall out of alignment with real-world exposure.
This guide sets out what to consider before accepting your personal insurance renewal and why a considered review protects far more than just your assets.
Why Insurance Renewal Is a Critical Personal Milestone
Life does not stand still, and similarly, risks keep moving. Inflation continues to drive up building costs, labour rates, and material prices. Vehicle repairs become more expensive as the cost of parts rises and supply chains tighten. Extreme weather events, including flooding, hail, and severe storms, are more frequent and more damaging.
Power surges linked to load shedding place ongoing strain on appliances and electronics. At the same time, many households have changed how they live and work. Home offices, renovations, additional drivers, and lifestyle upgrades change the variables, and before you know it, your lifestyle changes have completely altered your risk profile.
Insurance must evolve alongside these realities, and renewal is the moment to ensure that it does.
Review Your Sums Insured and Avoid Underinsurance
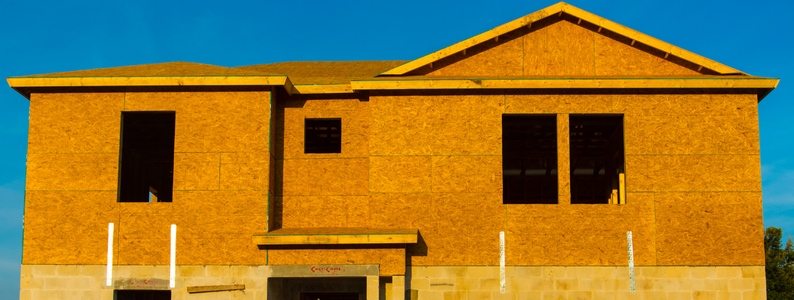
One of the most common issues uncovered at renewal is underinsurance. This unpleasant surprise often happens when sums insured remain unchanged year after year.
Building cover, for instance, should reflect replacement value, not market value. Construction costs, professional fees, demolition, and compliance requirements all affect what it would cost to rebuild. Contents cover should account for accumulated purchases and lifestyle changes over time. Vehicles may require value adjustments depending on age, use, or replacement costs.
Specified items such as jewellery, electronics, art, and collectibles need regular updates. If values fall short, the average clause may apply at the time of a claim , reducing payouts proportionally. Rising construction and replacement costs make outdated valuations a growing risk.
Disclose Lifestyle Changes – Fully
Insurance relies on accurate disclosure and leaving out information, even unintentionally, can affect claims.
Renewal is the time to disclose renovations, extensions, or structural changes. Here are some examples:
- Security upgrades or removals should be noted.
- Working from home or running a business from home should be disclosed, as it changes your exposure.
- New drivers, increased travel, or the purchase of portable valuables should also be disclosed.
Clear disclosure ensures that cover responds as expected when it is needed most.
Evaluate Excess Structures Carefully
Your excess levels influence both your premium and your claim experience. A higher excess can reduce premiums, but it must remain realistic.
At renewal, consider whether current excesses still suit your financial position and risk tolerance. Ask how excess adjustments affect premiums and whether the trade-off makes sense. Decisions should balance affordability with the likelihood and impact of claims, rather than focusing only on cost reduction.
Consider Emerging and Often Overlooked Risks
Renewal offers an opportunity to look beyond the obvious.
Personal liability cover protects against claims arising from injury or damage to third parties. Cyber and identity theft risks continue to grow as personal data exposure increases. Extreme weather risks may require specific attention, particularly flood, storm, and hail exposure.
Power surge damage linked to load shedding remains a significant concern. Theft trends also vary by area and can change over time. Reviewing these risks ensures that cover keeps up with evolving vulnerabilities.
Understand Premium Adjustments
Premium increases are rarely arbitrary. Inflation, higher repair costs, increased claims frequency, and reinsurance pressures all influence pricing across the market.
Individual risk profiles also play a role. Changes in asset values, claims history, location-based risks, and cover enhancements can affect premiums. Understanding why adjustments occur helps policyholders make informed decisions, rather than reacting with frustration or uncertainty.
The Value of a Professional Insurance Review
A professional review turns renewal into a strategic exercise. Advisors assess cover holistically, identify gaps, and ensure that asset values reflect current realities. They benchmark policies, explain complex wording, and negotiate with insurers where appropriate.
Most importantly, they advocate for clients when claim time comes. This advisory role transforms insurance from a product into an active risk management partnership focused on financial security and peace of mind.
Insurance renewal is not an administrative task. It is a strategic opportunity to protect your assets, lifestyle, and financial stability.
Engaging early allows time for meaningful review and informed decisions, rather than rushed acceptance. Before approving your next renewal, ensure your cover reflects your current reality.
Speak to Indwe for a comprehensive personal insurance review: https://indwe.co.za/personal.php
Indwe Risk Services is an authorised Financial Services Provider FSP 3425